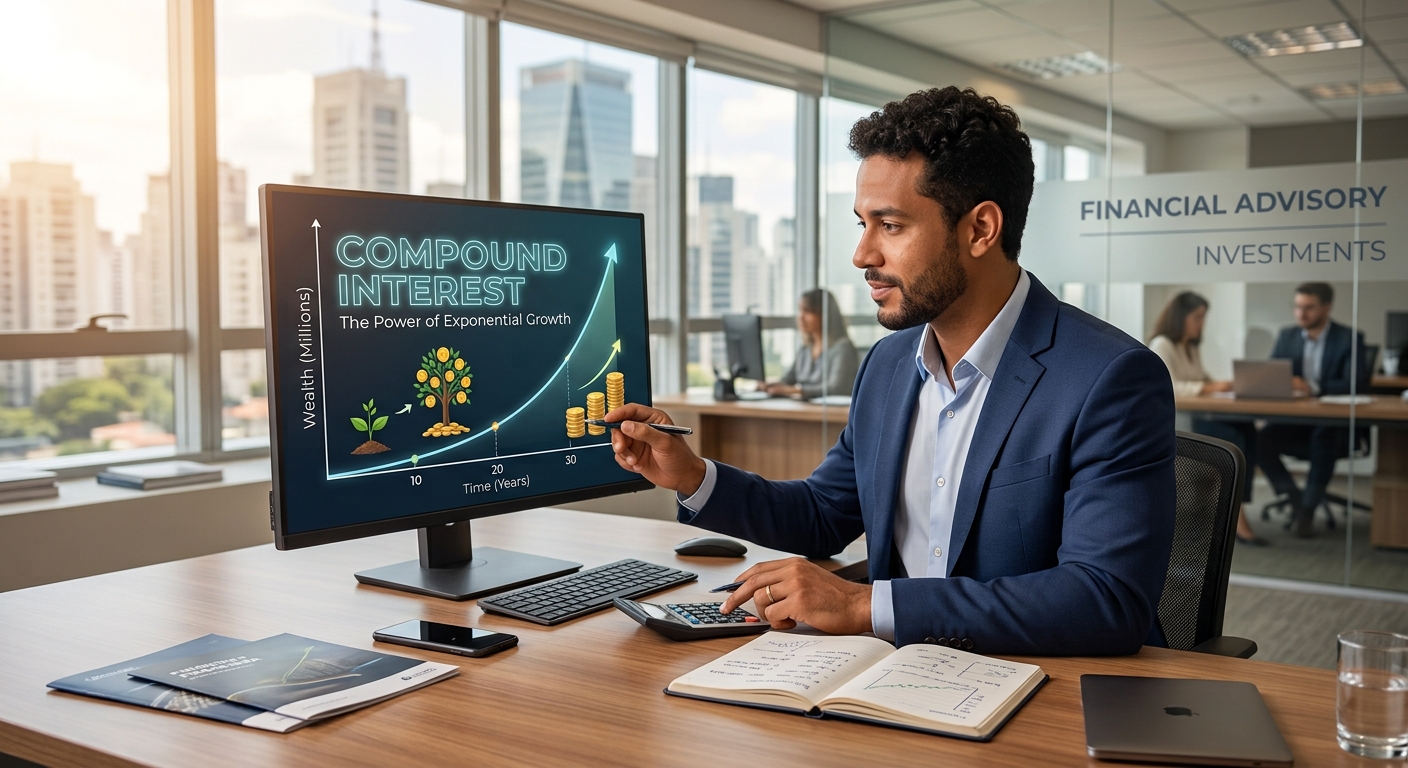
Compound interest is one of the simplest concepts in personal finance, but its long-term effects can be surprisingly powerful.
The basic principle is straightforward: money can generate returns, and those accumulated returns can eventually generate additional returns of their own.
Over a few months or even a couple of years, the difference may not seem dramatic. Over decades, however, compounding can have a much larger effect on savings and investments.
This is why time plays such an important role in long-term financial planning.
A person does not necessarily need to begin with a large amount of money to benefit from compounding. Regular contributions, reinvested returns, reasonable costs and enough time can all contribute to long-term growth.
At the same time, compound interest is not a guaranteed path to wealth. Investment returns can fluctuate, fees can reduce results and inflation can weaken purchasing power.
Compounding can even work against consumers when interest accumulates on unpaid debt.
Understanding how the process works can therefore help people make better decisions about both saving and borrowing.
What Is Compound Interest?
Interest can be understood as either the cost of borrowing money or the return earned from certain savings and investments.
Compound interest occurs when interest or investment returns are added to an existing balance and future returns are then calculated using that larger amount.
Consider a simple example.
Suppose someone deposits $1,000 into an account earning 5% annually.
After one year, a 5% return would equal $50, bringing the balance to $1,050.
If the $50 remains in the account, the next year’s return is no longer being calculated only on the original $1,000. It is calculated on $1,050.
At 5%, that would produce $52.50 rather than $50.
The difference is only $2.50 in this example.
But the same process can repeat year after year.
As the balance becomes larger, the amount generated by the same percentage return can also increase.
That is the foundation of compounding.
Simple Interest and Compound Interest Are Different
Simple interest does not produce the same effect.
Under a simple-interest calculation, interest is based on the original principal.
If $1,000 earns simple interest of 5% annually, it generates $50 each year.
After 10 years, ignoring other factors, the interest generated would total $500.
Compound interest works differently because previous interest becomes part of the balance used for future calculations.
The longer the process continues, the greater the potential difference between simple and compound growth.
Investor.gov provides a compound-interest calculator that allows users to experiment with different assumptions, including an initial investment, regular contributions, time horizon, estimated rate of return and compounding frequency.
These tools can help illustrate an important principle: time can have a major influence on the outcome.
Why Time Matters So Much
Compounding is generally more noticeable over long periods than short ones.
Imagine two investors contributing similar amounts toward retirement.
One begins at age 25.
The other waits until age 35.
The first investor has an additional decade during which contributions can potentially generate returns.
But the advantage is not limited to the amount contributed during those first 10 years.
Those early contributions also have more time to potentially generate returns, which can then generate additional returns.
That creates a compounding advantage.
This does not mean someone who begins investing later cannot build meaningful wealth.
Starting at 40, 50 or even later can still be valuable.
The principle simply demonstrates that, when all other factors are equal, money invested earlier has more time to work.
Regular Contributions Can Be More Important Than a Large Starting Balance
A common misconception is that investing is useful only for people who already have substantial amounts of money.
Compounding does not require a large initial investment.
Consistent contributions can gradually build the amount of capital available to grow.
Suppose someone invests a fixed amount every month.
The first contribution has the longest potential period to generate returns.
The second has slightly less time.
The process continues with every contribution.
Over many years, the combination of new contributions and accumulated returns can become significant.
This is why consistency is often an important part of financial planning.
Waiting until enough money is available to make one enormous investment can mean losing valuable time.
A smaller amount invested regularly may be easier to maintain and can create a disciplined savings habit.
Reinvesting Returns Helps Compounding Continue
Compounding depends partly on what happens to the returns an investment produces.
If interest, dividends or other earnings are withdrawn and spent, that money is no longer available to generate future returns.
If the earnings are reinvested, they become part of the capital base.
Imagine an investment generating a dividend.
An investor could take that payment as cash and spend it.
Alternatively, the investor might reinvest it by purchasing additional shares.
Those additional shares can potentially generate future dividends and capital appreciation.
Over a long enough period, reinvestment can become an important part of total growth.
Whether reinvestment is appropriate depends on the investor’s goals, income needs and financial circumstances, but understanding its relationship with compounding is essential.
The Mathematics Behind Compound Interest
A simplified compound-interest formula is:
A = P(1 + r/n)^(nt)
In this formula, A represents the final amount, P represents the initial principal, r is the annual interest rate, n represents how many times interest compounds each year and t represents the number of years.
The formula demonstrates several important relationships.
A larger starting amount can increase the final balance.
A higher rate can accelerate growth.
More frequent compounding can influence the result.
And a longer time horizon gives the process more opportunities to repeat.
Real investments, however, rarely behave as neatly as a mathematical example.
Stock-market returns are not fixed.
Interest rates can change.
Investments can lose value.
Taxes, fees and withdrawals can also affect actual results.
The formula is therefore useful for understanding the principle, but it should not be interpreted as a guarantee of future investment performance.
Compound Growth Can Work Against Borrowers
Compounding is often presented as something positive, but the mathematics does not care whether someone is saving or borrowing.
Interest can accumulate on debt as well.
This is especially important with expensive consumer debt.
If interest is added to an outstanding balance and the borrower does not reduce that balance sufficiently, future interest can be charged on a larger amount.
Debt can therefore become progressively more difficult to repay.
Credit cards are an important example because interest rates can be high and consumers may continue making new purchases while carrying existing balances.
A person investing money while simultaneously carrying expensive debt should understand both sides of the equation.
Earning a return on investments may be helpful, but paying high interest on debt can offset financial progress.
Compounding is powerful in either direction.
Inflation Can Reduce the Real Value of Growth
Seeing an investment account balance increase does not necessarily mean purchasing power has increased by the same amount.
Inflation changes the calculation.
Suppose an account earns 5% during a period when consumer prices rise by 4%.
The account has grown in nominal terms, but the investor’s purchasing power has increased by considerably less than 5%.
This is the difference between nominal and real returns.
Nominal return measures growth before accounting for inflation.
Real return considers the effect of rising prices.
The distinction becomes particularly important over long periods.
Retirement planning may involve decades of saving followed by decades of withdrawals.
A dollar in the future may not purchase the same amount of goods and services as a dollar today.
Long-term financial planning should therefore consider not only how much money may accumulate but also what that money may actually be able to buy.
Fees Also Compound — in the Wrong Direction
Investment costs can appear small when expressed as annual percentages.
Over long periods, however, recurring fees can have a larger effect than investors expect.
The reason is connected to compounding.
Money paid in fees is not simply lost once.
It is also money that is no longer invested and therefore cannot generate future returns.
Imagine two investments with similar performance before fees but significantly different annual costs.
Over one year, the difference may appear minor.
Over several decades, the cumulative impact can become much larger.
This is why investors should understand expense ratios, management fees, transaction costs and other charges associated with financial products.
Investor.gov provides educational resources designed to help consumers understand how investment fees can affect long-term outcomes.
Lower cost does not automatically mean a financial product is better, but cost should be part of the evaluation.
Higher Returns Usually Mean Higher Risk
Compound-interest examples often use fixed rates because they make the mathematics easier to understand.
Investments do not necessarily provide fixed returns.
An investment offering higher potential returns usually involves some form of additional risk.
Stocks can decline.
Companies can fail.
Bond prices can fluctuate.
Economic conditions can change.
This is why investors should be skeptical of anyone promising unusually high returns with little or no risk.
Investor.gov identifies promises of guaranteed high investment returns with minimal risk as a potential warning sign of investment fraud.
Compounding can magnify successful returns over time, but it cannot eliminate investment risk.
Starting Early Does Not Mean Taking Excessive Risk
The importance of time can sometimes be misunderstood as an argument for aggressive investing.
They are separate issues.
A younger investor may have a longer time horizon, but that does not automatically mean every high-risk investment is appropriate.
Asset selection should still consider financial goals, risk tolerance, diversification and when the money will be needed.
The advantage of starting early is simply that investments have more time to potentially grow.
An investor does not need extraordinary returns for time to become valuable.
Consistency and longevity can be powerful on their own.
How to Apply Compounding to Everyday Financial Planning
The principle of compound growth can influence several practical financial decisions.
Starting to save as early as reasonably possible gives money more time to work.
Regular contributions can reduce dependence on trying to identify the perfect moment to invest.
Reinvesting returns, when appropriate, can keep more capital participating in future growth.
Monitoring fees helps prevent unnecessary costs from reducing the amount available to compound.
Managing expensive debt is equally important because compound interest can work against borrowers.
And maintaining a long-term perspective can help investors avoid making every decision based on short-term market movements.
These habits are not complicated.
Their potential value comes from repeating them over long periods.
Compounding Is Not a Shortcut to Becoming Rich
Compound interest is powerful, but it should not be treated as a financial miracle.
Three ingredients are generally required: capital, returns and time.
Regular contributions can increase the capital.
Investment performance can generate returns.
Time allows the process to repeat.
Remove one of those factors and the result changes significantly.
Someone investing very small amounts cannot reasonably expect compounding alone to create enormous wealth quickly.
Similarly, an investor pursuing extremely high returns to accelerate the process may expose capital to substantial risk.
Successful long-term financial planning is therefore usually less exciting than advertisements promising rapid wealth.
It involves saving, controlling costs, managing risk and remaining consistent.
The Most Valuable Part of Compounding Is Time
The most important lesson behind compound interest is not the formula.
It is the relationship between money and time.
Financial progress can appear frustratingly slow in the beginning because the initial balance is relatively small.
As savings and accumulated returns increase, however, the same percentage return applies to a larger amount of capital.
That is when compounding becomes increasingly visible.
For this reason, seemingly modest financial decisions can have consequences that become much larger over decades.
Saving consistently, reinvesting returns, controlling unnecessary fees and avoiding expensive debt may not transform someone’s finances immediately.
But long-term wealth is rarely created by one isolated financial decision.
It is ofte