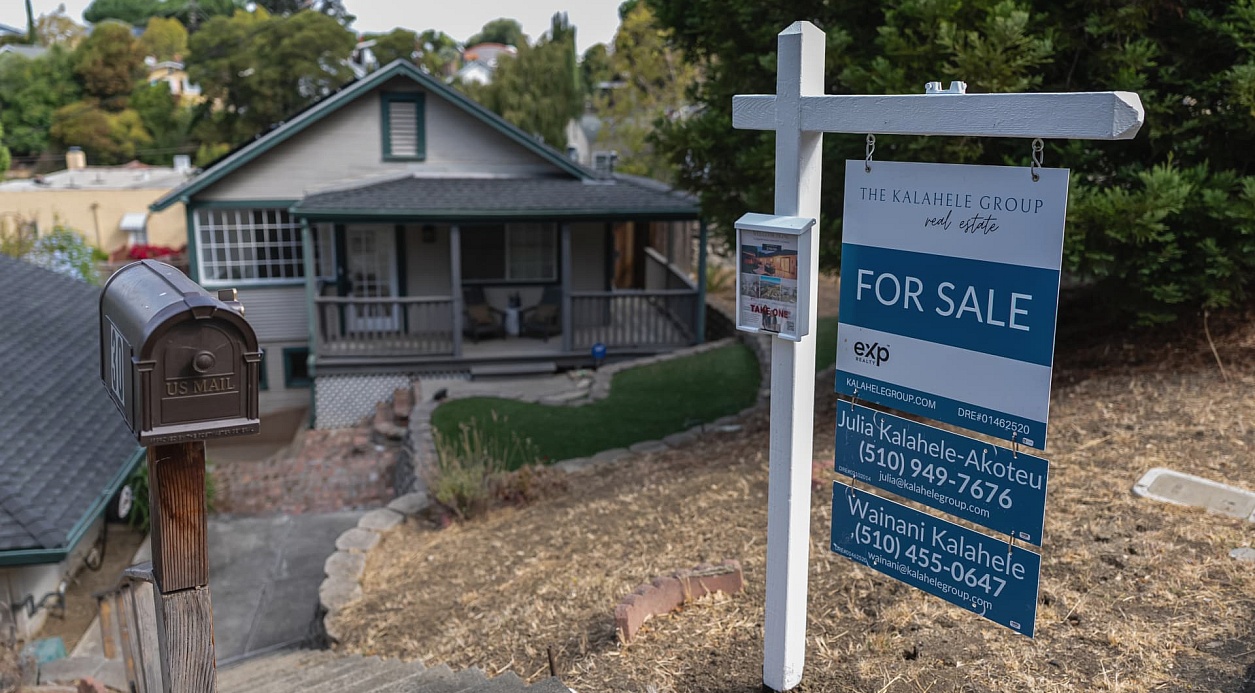
U.S. existing home sales declined in August as higher mortgage rates continued to challenge affordability and keep many potential buyers on the sidelines, even as the number of homes available for sale increased.
Sales of previously owned homes fell 2% from July to a seasonally adjusted annualized rate of 3.98 million units, according to the National Association of Realtors.
The decline brought existing home sales to their slowest pace since June 2025 and highlighted the continuing sensitivity of the housing market to borrowing costs.
Regional weakness was particularly noticeable in the Northeast and Midwest, where sales experienced the largest declines.
The August numbers largely represent closings on contracts signed in June and July, a period that included a sharp increase in mortgage rates during the middle of July. Because home purchases typically take time to move from contract signing to closing, changes in borrowing costs often appear in sales data with a delay.
Lawrence Yun, chief economist for the National Association of Realtors, pointed to the traditional inverse relationship between mortgage rates and home sales.
When mortgage rates rise, affordability deteriorates and sales activity tends to weaken. When borrowing costs fall, buyers can generally finance more expensive homes with the same monthly budget, potentially stimulating demand.
Despite August’s monthly decline, the housing market has shown some improvement compared with 2025. Existing home sales through August were up 1.6% on a year-to-date basis from the same period a year earlier.
But the latest data show that a sustained housing recovery remains highly dependent on mortgage rates, affordability and inventory.
Mortgage Rates Continue to Shape Housing Demand
Mortgage rates have become one of the most important forces determining activity in the U.S. housing market.
Even relatively small changes in rates can significantly alter monthly payments because mortgages are typically large loans repaid over decades.
For a buyer financing hundreds of thousands of dollars, a higher interest rate can add a substantial amount to the monthly cost of homeownership.
That creates several possible responses.
Some buyers reduce their budgets and search for less expensive properties.
Others increase their down payments.
Some postpone purchases entirely and wait for borrowing conditions to improve.
The effect becomes particularly significant when home prices are already elevated.
Buyers are therefore dealing with two affordability challenges simultaneously: expensive properties and relatively high financing costs.
August’s decline in sales illustrates how quickly housing activity can respond when mortgage rates move higher.
Housing Inventory Reached Its Highest Supply Level in More Than a Decade
One of the most important developments in the August report was the increase in available homes.
Housing inventory reached 1.62 million units at the end of the month.
That represented a 3.2% increase from July and a 5.9% increase compared with August 2025.
At the current sales pace, available inventory represented approximately 4.9 months of supply.
That was the highest level recorded in more than a decade.
The increase could provide some relief to buyers who spent years competing in a market characterized by extremely limited inventory.
More homes for sale can give buyers additional choices and potentially reduce the pressure to make immediate offers.
It can also give buyers greater negotiating power in markets where properties are taking longer to sell.
However, the national numbers do not mean every local market suddenly has abundant inventory.
Housing remains highly regional.
Some areas continue to experience tight supply, while others have seen more substantial increases in available properties.
More Inventory Has Not Stopped Home Prices From Rising
Despite the increase in supply and decline in sales activity, U.S. home prices continued to rise.
The median price of an existing home sold in August reached $429,100.
That was 1.6% higher than in August 2025 and represented a new record for the month of August.
The combination of slower sales, greater inventory and higher prices may initially appear contradictory.
But several factors can explain the trend.
Inventory can increase while remaining relatively limited compared with long-term housing needs.
The types of homes being sold can also influence median prices.
If a larger share of transactions occurs in expensive price categories, the national median can rise even if individual properties are not experiencing dramatic appreciation.
Regional differences also matter.
The Northeast recorded particularly strong price increases while continuing to have the lowest inventory levels.
Limited supply can support prices even when overall sales volumes decline.
The West Was the Only Region to Record a Price Decline
Housing conditions varied significantly across the country.
The Northeast experienced some of the strongest price growth while also maintaining the tightest supply conditions.
That relationship demonstrates one of the basic forces affecting housing prices.
When many buyers compete for relatively few properties, prices can remain supported.
When supply becomes more available relative to demand, buyers may gain negotiating power.
The West was the only region where the median home price declined compared with the previous year.
This regional divergence is important because national housing statistics can conceal dramatically different local conditions.
A buyer in a supply-constrained Northeastern market may encounter a very different environment from someone shopping for a home in a Western market where inventory and price dynamics are changing.
Real estate is ultimately local, even when national mortgage rates affect nearly everyone.
Lower-Priced Homes Are Seeing Greater Weakness
The distribution of sales by price range provided another important signal about housing affordability.
Sales of homes priced between $100,000 and $250,000 fell 10% from August 2025.
At the other end of the market, homes priced above $1 million recorded a 3.9% year-over-year increase in sales.
The luxury category was the only price segment to experience annual growth.
This divergence suggests that financial pressure is not affecting all buyers equally.
Consumers shopping in lower price ranges are often more dependent on mortgage financing.
Higher interest rates can therefore have an immediate effect on what they can afford.
A buyer with a strict monthly housing budget may no longer qualify for the same loan amount when rates rise.
Affluent buyers purchasing million-dollar properties may have greater financial flexibility.
They may make larger down payments, have more diversified sources of wealth or purchase homes entirely with cash.
The result is a housing market where expensive properties can continue attracting demand even as affordability problems weigh on lower-priced segments.
Cash Buyers Remain an Important Part of the Market
Cash transactions accounted for 27% of existing home sales in August.
That was slightly higher than in July, although marginally below the share recorded in August of the previous year.
A large cash-buyer presence can influence market dynamics.
Cash purchasers are not directly affected by mortgage rates because they do not need to finance the transaction.
That gives them an advantage when borrowing costs are high.
Sellers may also prefer cash offers because they can involve fewer financing contingencies and potentially lower the risk of a transaction failing before closing.
For mortgage-dependent buyers, competing against cash can make an already difficult affordability environment more challenging.
The persistence of cash transactions helps explain why some housing demand can remain resilient even when mortgage rates increase.
First-Time Buyers Increased Their Share Slightly
First-time homebuyers represented 30% of August sales.
That was a small increase from both July and August of the previous year.
The improvement is notable because first-time buyers can be particularly vulnerable to affordability pressures.
Unlike existing homeowners, they generally cannot use equity from the sale of another property toward their purchase.
They must assemble a down payment while dealing with mortgage rates, home prices, closing costs, insurance and other expenses associated with homeownership.
A modest increase in their share of sales could suggest that some first-time buyers are finding opportunities as inventory improves.
More available properties and slower sales may reduce bidding pressure in certain markets.
However, affordability remains a major obstacle.
A larger share of transactions going to first-time buyers does not necessarily mean purchasing a home has become broadly affordable.
Investors and Second-Home Buyers Pulled Back
Investors and second-home buyers represented 15% of August transactions.
That was a substantial decline from the 21% share recorded in August 2025.
The reduction may create some opportunities for traditional owner-occupants.
When investors are highly active, they can compete directly with families and first-time buyers for available homes.
A lower investor share potentially reduces some of that competition.
Higher financing costs can also influence investment-property decisions.
Real estate investors often evaluate purchases based on the relationship between property prices, expected rental income, financing expenses and potential appreciation.
As borrowing costs rise, some deals that looked attractive under lower interest rates may no longer generate acceptable returns.
This can reduce investor demand even while cash-rich buyers remain active in selected markets.
Homes Are Taking Longer to Sell
Another indication of cooling market conditions is the amount of time properties are spending on the market.
Homes sold in August were typically on the market for 31 days, compared with 29 days in July.
Two additional days may not sound significant, but the direction of the trend matters.
When properties sell extremely quickly, sellers generally have greater leverage.
Buyers may feel pressure to submit offers immediately, waive certain conditions or compete with multiple bidders.
As homes remain available longer, buyers can potentially take more time to evaluate properties and negotiate.
Sellers may also need to become more realistic about pricing.
If the trend continues, the market could gradually become more balanced between buyers and sellers.
Higher Inventory Could Eventually Help Affordability
The increase in available homes may become one of the most important developments for the housing market.
For years, insufficient supply has contributed to upward pressure on prices.
If inventory continues expanding while demand remains constrained by high mortgage rates, price growth could moderate.
That does not necessarily mean home prices will decline nationally.
Housing prices depend on local supply, employment, population growth and many other factors.
But slower price appreciation combined with stable or declining mortgage rates could eventually improve affordability.
The challenge is that these changes can take time.
Even after inventory begins increasing, sellers may resist reducing prices, particularly if they do not urgently need to move.
Existing Homeowners Face a Mortgage Lock-In Problem
Another factor affecting housing supply is the difference between current mortgage rates and the rates many homeowners already have.
Homeowners who secured low fixed mortgage rates in previous years may be reluctant to sell.
Moving could require giving up an inexpensive mortgage and financing another property at a much higher rate.
That creates a financial incentive to remain in the existing home.
The effect is sometimes described as mortgage rate lock-in.
It can limit the number of homes available for sale and reduce transaction activity.
If mortgage rates eventually decline, some homeowners may become more willing to list their properties, potentially increasing both supply and sales.
Buyers May Gain Negotiating Power Even Without Lower Prices
An improving buyer environment does not always appear through falling headline home prices.
Negotiating conditions can change in other ways.
A property that remains on the market longer may give buyers more opportunity to request repairs, negotiate closing costs or submit offers below the original asking price.
Sellers may become more willing to make concessions when they receive fewer competing offers.
This means the experience of purchasing a home can improve even while national median prices remain elevated.
The rise to a 4.9-month housing supply suggests the balance between buyers and sellers is gradually changing.
The Housing Market Remains Highly Sensitive to Interest Rates
August’s housing data present a mixed picture.
Existing home sales fell 2% to an annualized pace of 3.98 million, the weakest rate since June 2025.
At the same time, year-to-date sales remained 1.6% higher than a year earlier.
Inventory increased to 1.62 million homes, providing 4.9 months of supply and reaching its highest level in more than a decade.
Yet the median home price still climbed 1.6% year over year to a record August level of $429,100.
The biggest divide may be appearing between different types of buyers.
Lower-priced home sales have weakened sharply, while transactions above $1 million continue growing.
Cash buyers remain influential, while investors and second-home purchasers have reduced their share of the market.
For prospective homebuyers, the increase in inventory provides some encouraging news.
More supply and longer selling times can improve negotiating conditions.
But affordability remains constrained by the combination of elevated prices and mortgage rates.
The direction of borrowing costs will therefore remain one of the most important factors determining what happens next.
If mortgage rates decline, demand could strengthen as previously sidelined buyers return.
If rates remain elevated or move higher, sales may continue struggling even as inventory improves.
For now, the August numbers show a housing market gradually offering buyers more choices — but not yet providing the broad affordability relief many households have been waiting for.