Wholesale inflation in the United States remained elevated in August, reinforcing concerns that price pressures are proving difficult to contain just as the Federal Reserve prepares for a closely watched interest rate decision.
The producer price index, or PPI, increased 0.4% during the month, according to data released by the Bureau of Labor Statistics. The result matched economists’ expectations but still pointed to persistent inflation throughout the U.S. economy, particularly in energy and goods.
On an annual basis, producer prices were 5.4% higher than a year earlier, slightly exceeding analysts’ forecasts. The latest figures arrive at a critical moment for monetary policy, with investors increasingly expecting the Federal Reserve to resume interest rate increases after keeping its benchmark rate unchanged through much of 2026.
Markets reacted quickly to the report. U.S. stock futures declined while Treasury yields moved sharply higher. The yield on the benchmark 10-year Treasury note climbed to its highest level since November 2023 as traders reassessed how long interest rates may need to remain elevated.
At the same time, U.S. crude oil prices moved above $100 per barrel, creating another potential source of inflation for consumers and businesses.
Together, the developments have intensified the debate over whether the Federal Reserve needs to tighten monetary policy again to prevent inflation from becoming entrenched.
Producer Inflation Remains Elevated
The PPI measures the prices that domestic producers receive for goods and services and is closely monitored as an indicator of inflationary pressure before it reaches consumers.
August’s 0.4% monthly increase followed a revised 0.1% gain in July. The previous estimate had shown no change for July, making the revision another indication that wholesale inflation has been somewhat stronger than initially reported.
The annual increase of 5.4% remains well above levels consistent with the Federal Reserve’s longer-term inflation objective.
Although the central bank does not directly target the PPI, sustained increases in producer costs can eventually affect consumer prices as companies attempt to protect profit margins.
Businesses facing higher costs for fuel, transportation, raw materials and other inputs have several choices. They can absorb those expenses, improve efficiency or pass at least part of the increase to customers.
If higher producer costs persist, passing them along through higher consumer prices becomes increasingly likely.
That is one reason Federal Reserve officials closely examine inflation throughout the supply chain rather than focusing exclusively on consumer prices.
Core Inflation Offered Some Encouragement
Not every component of the report pointed toward accelerating inflation.
Core PPI, which excludes the more volatile food and energy categories, increased 0.2% in August. Economists had expected a 0.3% rise.
The softer core figure suggests that some underlying price pressures may be more contained than the headline number indicates.
Another measure that excludes food, energy and trade services increased 0.3%, matching forecasts.
These details complicate the interpretation of the report.
Headline producer inflation was relatively strong, but much of the increase was concentrated in categories heavily influenced by energy prices.
For Federal Reserve policymakers, determining whether those pressures will remain isolated or spread throughout the broader economy will be critical.
Temporary energy shocks do not necessarily require aggressive monetary policy responses. However, sustained increases in fuel and transportation costs can eventually influence a much wider range of prices.
Energy Prices Drove Much of the Increase
Energy was one of the largest contributors to August’s producer inflation.
Final demand energy prices jumped 4.2% during the month.
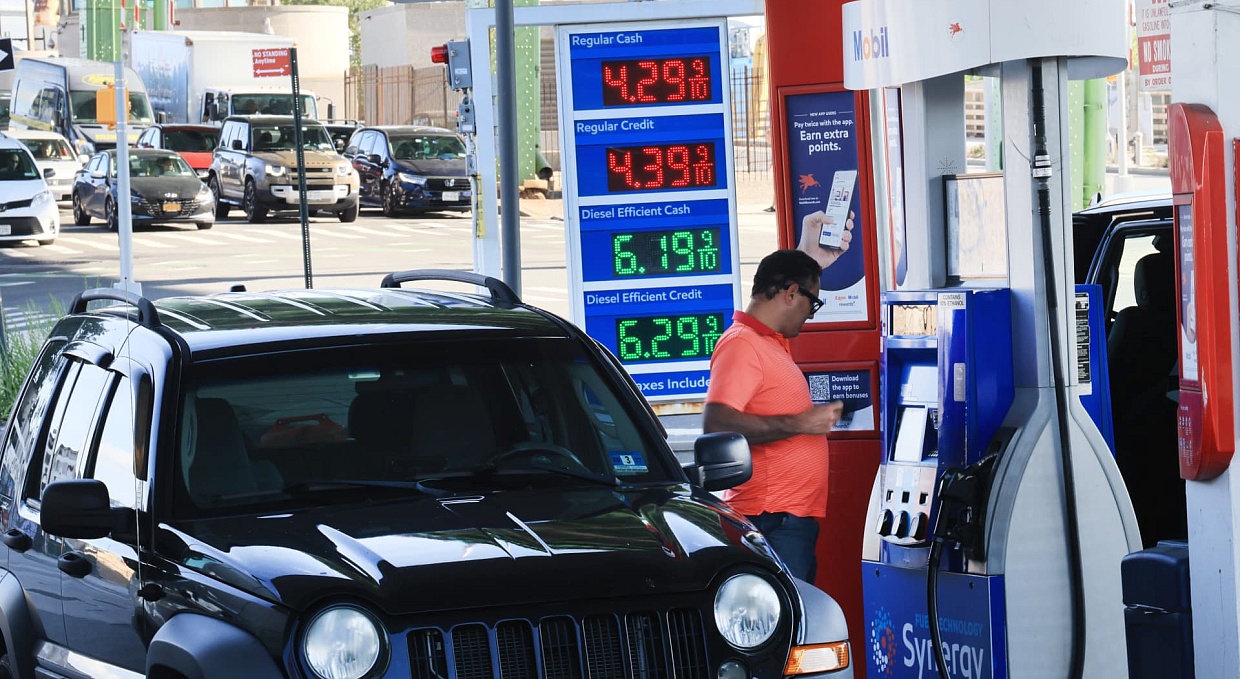
Diesel prices were particularly notable, rising 24.1%.
A sharp increase in diesel prices can have consequences far beyond the energy sector because diesel remains essential to freight transportation, agriculture, construction and industrial activity.
Higher fuel costs make it more expensive for trucking companies to transport products across the country. Those costs can then affect retailers, manufacturers and ultimately consumers.
Goods prices overall increased 1.1% in August.
Services inflation was considerably more moderate, rising only 0.1%.
Within services, however, transportation and warehousing costs increased 2.3%, accounting for a significant portion of the monthly increase.
This combination of higher energy and transportation expenses could become particularly important if elevated oil prices persist.
Oil Above $100 Adds Another Inflation Risk
The PPI report arrived on the same day that U.S. crude oil prices climbed above $100 per barrel.
The increase in oil prices has been linked in part to geopolitical tensions in the Middle East, adding another unpredictable variable to the inflation outlook.
Energy prices influence virtually every major economy.
Consumers feel the impact directly through gasoline and utility costs, while businesses experience higher transportation, manufacturing and logistics expenses.
For the Federal Reserve, oil presents a difficult challenge because interest rate policy cannot directly increase energy supplies.
Higher borrowing costs will not produce additional barrels of oil or resolve geopolitical conflicts.
However, the central bank may still need to respond if higher energy prices begin influencing broader inflation expectations.
If households and businesses start expecting prices to continue rising, those expectations can influence wage negotiations, purchasing behavior and corporate pricing decisions.
That can make inflation more persistent.
Pipeline Inflation Signals Remain
Other parts of the PPI report also suggested that price pressures remain present deeper within the production process.
Prices for processed goods increased 1.8% in August, while unprocessed goods rose 1.1%.
These categories can provide clues about future inflation because they capture costs at earlier stages of production.
If companies continue paying more for intermediate materials, some of those costs may eventually move into finished products.
Portfolio management prices, meanwhile, declined 1.6% during August.
Despite the monthly decline, the category remains 18.8% higher than a year earlier.
The mixed figures reinforce the complexity of the current inflation environment.
Some service categories are showing moderation, while energy and goods remain under significant upward pressure.
Treasury Yields Jump as Markets Reassess Rates
Financial markets responded quickly to the inflation report.
Stock futures declined as investors considered the possibility of tighter monetary policy, while Treasury yields surged.
The 10-year Treasury yield reached its highest level since November 2023.
Higher Treasury yields can affect financial markets well beyond government bonds.
Mortgage rates, corporate borrowing costs and other forms of credit are often influenced by Treasury yields.
Higher yields can also create pressure on equity valuations because investors have access to more attractive returns from fixed-income assets.
Chris Rupkey, chief economist at Fwdbonds, said the latest PPI figures maintain a sense of urgency around inflation and provide additional support for policymakers who believe monetary policy should remain restrictive.
The market reaction suggests investors are taking that possibility seriously.
CPI Becomes the Next Major Test
Attention will now turn to the upcoming consumer price index report.
Economists expect headline CPI inflation to run at approximately 3.4% annually, while core inflation — excluding food and energy — is forecast at around 2.4%.
The CPI report will provide a more direct picture of the inflation consumers are experiencing.
A stronger-than-expected reading could reinforce expectations for another Federal Reserve rate increase.
A weaker report could provide policymakers with more room to wait before tightening monetary policy again.
However, the Federal Reserve does not rely on either PPI or CPI alone.
Information from both reports contributes to broader inflation calculations, including the personal consumption expenditures price index.
PCE Remains the Fed’s Preferred Inflation Gauge
The Federal Reserve primarily evaluates inflation using the personal consumption expenditures, or PCE, price index.
The next PCE report is scheduled for later this month and could provide another important signal about the direction of monetary policy.
PCE differs from CPI in several ways, including how different goods and services are weighted and how changes in consumer behavior are incorporated.
Federal Reserve officials generally consider it a broader representation of consumer inflation.
Still, PPI and CPI data can provide valuable clues about where PCE may be heading.
Persistent increases in producer costs, combined with stronger consumer inflation, would make it more difficult for policymakers to argue that price pressures are moving sustainably toward the Fed’s target.
Markets Increasingly Expect a Rate Hike
Expectations for the Federal Reserve’s next meeting have shifted considerably.
After holding rates steady through much of 2026, policymakers are now widely expected to consider a quarter-percentage-point increase in the federal funds rate.
Following the PPI report, futures-market pricing indicated approximately a 66% probability of such an increase, according to CME Group’s FedWatch tool.
Those probabilities can change rapidly as new economic information becomes available.
The upcoming CPI report will therefore be particularly important.
A significant upside surprise could push expectations for a rate increase even higher, while softer inflation could cause traders to reconsider.
Federal Reserve Officials Remain Divided
Federal Reserve officials have expressed different views about how aggressively the central bank should respond.
Chairman Kevin Warsh has emphasized the importance of returning inflation toward the central bank’s target and has indicated that policymakers must remain prepared to act if price pressures fail to moderate.
Other officials have argued for a more cautious approach.
Their concern is that monetary policy operates with significant delays.
Previous rate increases may still be affecting borrowing, investment, housing and consumer demand, meaning additional tightening could create economic weakness that becomes visible only months later.
The debate reflects the central challenge facing the Federal Reserve.
Moving too slowly risks allowing inflation to remain elevated.
Moving too aggressively risks unnecessarily weakening the economy.
Tariffs and Geopolitical Risks Complicate the Outlook
Inflation pressures this year have also been connected to factors that monetary policy cannot easily control.
Tariffs can increase the cost of imported products and materials, while geopolitical tensions can disrupt global supply chains and commodity markets.
The conflict in the Middle East has become particularly important because of its influence on energy prices.
If oil remains above $100 for an extended period, the resulting transportation and production costs could spread into other parts of the economy.
That possibility could make the Federal Reserve less confident that inflation will continue falling without additional policy intervention.
The Fed’s Next Decision Becomes Increasingly Important
August’s producer inflation report does not guarantee that the Federal Reserve will raise interest rates.
It does, however, strengthen the argument that the inflation battle remains unfinished.
Headline producer prices increased 0.4%, annual PPI reached 5.4%, energy costs surged and oil moved above $100 per barrel.
At the same time, core producer inflation came in slightly below expectations, giving policymakers at least some evidence that underlying price pressures are not accelerating everywhere.
The upcoming CPI and PCE reports will help determine which side of that picture ultimately carries more weight.
For financial markets, the stakes are significant.
A renewed Federal Reserve tightening cycle could push borrowing costs higher, place additional pressure on stocks and keep Treasury yields elevated.
If inflation begins to moderate convincingly, policymakers could instead choose patience.
For now, however, the latest wholesale inflation figures provide another reminder that bringing U.S. inflation fully under control may prove more difficult — and take longer — than investors previously expected.