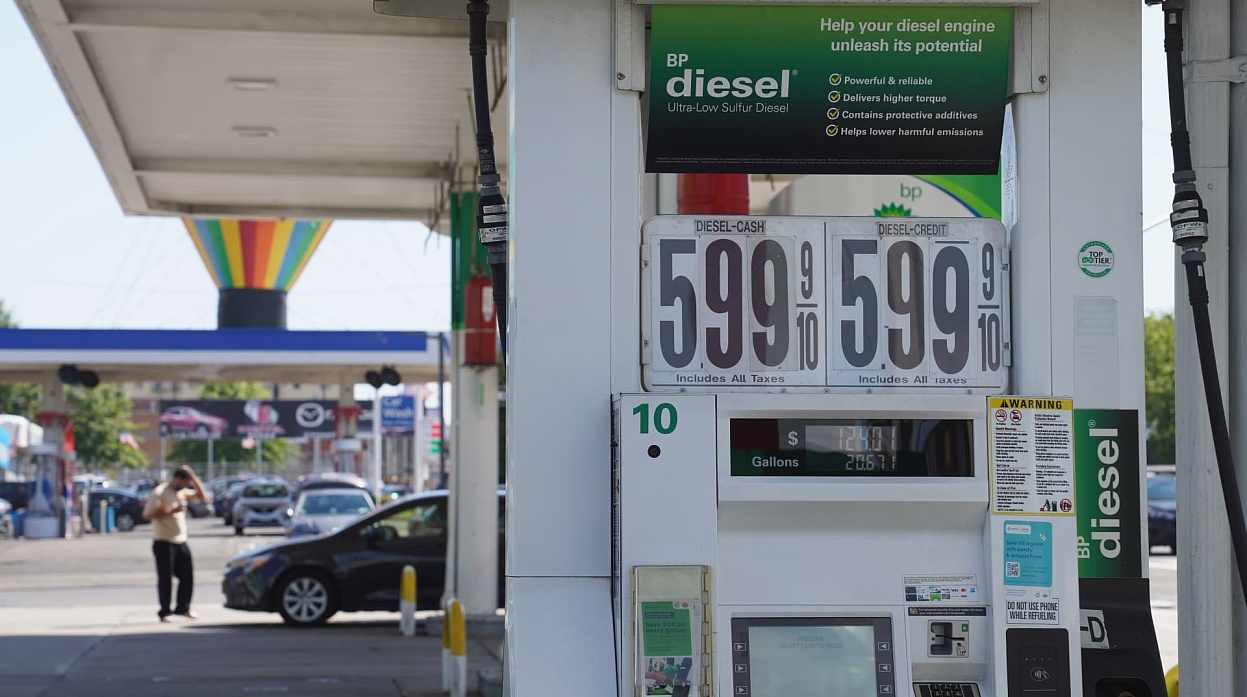
Expectations that the Federal Reserve could raise interest rates at its next policy meeting are climbing rapidly as investors confront renewed inflation pressures, rising commodity prices and a U.S. economy that continues to show signs of resilience.
Financial markets are increasingly pricing in another period of tighter monetary policy, with traders assigning roughly a 70% probability to an interest rate increase at the Federal Reserve’s upcoming meeting, according to indicators from CME Group’s FedWatch tool. Expectations for an additional increase before the end of the year have also risen to nearly 60%.
The shift represents a significant change in market sentiment as investors reassess the outlook for inflation and monetary policy.
A combination of stronger wholesale inflation, oil prices moving above $100 per barrel, resilient labor-market conditions and escalating geopolitical tensions has complicated the Federal Reserve’s effort to return inflation toward its long-term 2% target.
The next set of U.S. inflation figures could now play a decisive role in determining whether policymakers believe another rate increase is necessary.
Wholesale Inflation Adds Pressure on the Fed
One of the latest warning signals came from the U.S. producer price index, or PPI, which measures changes in prices received by domestic producers and is often used as an indicator of inflationary pressure moving through the supply chain.
Producer prices increased 0.4% in August.
While the monthly increase was only moderately above expectations, the combination of the August reading and an upward revision to July’s figures strengthened concerns that inflation may be proving more persistent than policymakers had hoped.
On an annual basis, PPI inflation reached 5.4%.
The significance of producer inflation extends beyond the immediate headline number.
When companies face higher costs for raw materials, transportation, energy and other inputs, they must decide whether to absorb those costs through lower profit margins or pass them along to customers through higher prices.
If businesses increasingly choose the latter, stronger wholesale inflation can eventually contribute to higher consumer prices.
That possibility is particularly important for the Federal Reserve as officials attempt to determine whether recent inflation pressures are temporary or evidence of a more persistent trend.
Oil Above $100 Creates Another Inflation Problem
Energy markets are adding another layer of uncertainty.
U.S. crude oil prices jumped approximately 4%, pushing above the psychologically important level of $100 per barrel as escalating conflict in the Middle East disrupted market expectations.
Higher oil prices can influence inflation through multiple channels.
The most obvious impact is at the gasoline pump, where consumers can face higher fuel costs.
But oil is also deeply integrated into the broader economy.
Higher energy prices can increase transportation and shipping expenses, raise manufacturing costs and make the movement of goods more expensive. Airlines, logistics companies, manufacturers and agricultural producers can all experience higher operating expenses when oil prices rise significantly.
Those additional costs can eventually spread throughout supply chains.
For the Federal Reserve, this creates a difficult policy problem.
Central banks cannot produce more oil or directly resolve geopolitical conflicts. However, they must respond if higher energy prices begin influencing broader inflation expectations and consumer behavior.
A temporary increase in oil prices may not justify tighter monetary policy on its own.
A prolonged energy shock, however, could make inflation more difficult to control.
Middle East Conflict Adds Economic Uncertainty
Geopolitical tensions have become another important variable for global central banks.
The ongoing conflict involving Iran has contributed to volatility across energy and commodity markets, increasing concerns about potential supply disruptions.
Oil markets are particularly sensitive to developments in the Middle East because of the region’s importance to global energy production and transportation.
Any threat to production facilities, shipping routes or major energy infrastructure can quickly influence global prices.
That uncertainty makes forecasting inflation considerably more difficult.
Even if domestic price pressures begin to moderate, an external commodity shock can reverse some of that progress.
The Federal Reserve therefore faces the challenge of distinguishing between temporary price volatility and inflation that could become embedded in the broader economy.
European Central Bank Moves Rates Higher
The Federal Reserve is not the only major central bank confronting renewed inflation concerns.
The European Central Bank recently raised its key interest rate by 0.25 percentage points while also increasing its inflation forecasts.
European policymakers cited concerns about the economic consequences of the Iran conflict as well as longer-term inflation risks.
The ECB’s decision illustrates the broader challenge facing central banks around the world.
After years of battling elevated inflation, policymakers must determine how long monetary policy needs to remain restrictive — and whether additional rate increases are necessary when new inflation shocks emerge.
Raising interest rates can help reduce demand and slow price increases, but tighter financial conditions also create risks for economic growth.
Higher rates increase borrowing costs for households and companies, potentially weakening investment, housing activity and consumer spending.
Central banks must therefore balance inflation control against the possibility of pushing their economies toward a significant slowdown.
CPI Report Could Shape the Federal Reserve’s Decision
Attention in the United States is now turning toward the upcoming consumer price index report from the Bureau of Labor Statistics.
Economists expect headline CPI inflation to increase approximately 3.4% from a year earlier.
Core CPI, which excludes volatile food and energy prices, is expected to rise approximately 2.4% annually.
Core inflation receives particularly close attention because it can provide policymakers with a clearer picture of underlying price trends.
Energy prices can move sharply because of geopolitical events, while food prices can fluctuate due to weather and other temporary factors.
Removing those categories can therefore help economists evaluate whether inflation is becoming entrenched across the broader economy.
A stronger-than-expected CPI report could reinforce expectations for a Federal Reserve rate increase.
Conversely, unexpectedly weak inflation data could reduce some of the pressure on policymakers.
However, even a relatively favorable consumer inflation report may not completely eliminate concerns created by producer prices and rising energy costs.
The Fed’s Preferred Inflation Measure Remains PCE
Although CPI receives significant attention from investors and consumers, it is not the Federal Reserve’s preferred inflation indicator.
Policymakers primarily focus on the personal consumption expenditures price index, commonly known as PCE inflation.
The latest available data showed headline PCE inflation running at 3.7% in July.
Core PCE, which removes food and energy prices, stood at 3.3%.
Both readings remain above the Federal Reserve’s long-term inflation target.
Economists estimate that August data could show core PCE increasing around 0.3% on a monthly basis.
Such a reading could strengthen the argument among policymakers who believe monetary conditions need to become more restrictive.
The Federal Reserve does not base its decisions on a single inflation report.
Officials instead evaluate a broad collection of economic indicators, including consumer prices, producer prices, employment, wage growth, consumer spending and inflation expectations.
The combination of those indicators ultimately determines how policymakers assess the balance of risks.
Strong Labor Market Complicates the Picture
The U.S. labor market represents another important consideration.
Jobless claims remain relatively low, indicating that companies are not dramatically increasing layoffs despite restrictive interest rates.
A resilient labor market is generally positive for the economy.
Strong employment supports household incomes and consumer spending.
From the Federal Reserve’s perspective, however, unusually strong demand can make inflation more difficult to reduce.
When businesses compete for workers, wages can rise. Higher labor costs can then encourage companies to increase prices, particularly in service industries where wages represent a significant portion of operating expenses.
The Fed does not necessarily want unemployment to rise.
Instead, policymakers are attempting to achieve a better balance between supply and demand throughout the economy.
The challenge is slowing inflation without causing unnecessary economic damage.
Some Economists Expect Multiple Rate Increases
Not everyone believes a single additional rate hike will be enough.
Bank of America senior U.S. economist Stephen Juneau has projected that the Federal Reserve could raise interest rates three times over the coming months.
That outlook is considerably more hawkish than current futures-market pricing.
If such a scenario materializes, financial markets could face a meaningful adjustment.
Higher policy rates generally increase yields across fixed-income markets and raise borrowing costs throughout the economy.
Mortgages, corporate loans and other forms of financing could become more expensive.
Equity valuations could also come under pressure because higher bond yields can make fixed-income investments more attractive relative to stocks.
At the same time, tighter monetary policy could strengthen the U.S. dollar, creating additional consequences for commodities and international markets.
Supply-Chain Inflation Remains a Concern
Investment strategists are also paying close attention to the difference between consumer and producer inflation.
Even if upcoming CPI figures appear relatively moderate, the recent PPI data suggest that inflationary pressures may still be moving through the supply chain.
That creates a potential delayed effect.
Companies do not always pass higher costs to customers immediately.
Some may initially accept lower margins before eventually increasing prices if elevated costs persist.
As a result, stronger producer inflation can sometimes provide an early warning of future consumer price pressures.
The recent increase in oil prices makes that possibility particularly relevant.
If energy remains expensive for an extended period, transportation and production costs could gradually appear in the prices consumers pay for a wide range of goods and services.
Fed Faces a Difficult Decision
The Federal Reserve’s upcoming decision will ultimately depend on how policymakers interpret the combined evidence.
Persistent wholesale inflation supports the case for tighter monetary policy.
Oil above $100 per barrel introduces another potential source of price pressure.
A resilient labor market suggests the economy may be capable of absorbing higher rates, while geopolitical uncertainty increases the risk of additional commodity shocks.
On the other side of the debate, policymakers must consider the delayed effects of previous rate increases.
Monetary policy often influences the economy with a lag, meaning the full impact of earlier tightening may not yet be visible.
Raising rates too aggressively could therefore create unnecessary economic weakness later.
That tension leaves the Federal Reserve with a narrow path.
Officials want convincing evidence that inflation is moving sustainably toward the 2% target, but they also want to avoid tightening financial conditions more than necessary.
The upcoming CPI report will provide another important piece of that puzzle.
But with producer prices rising, oil trading above $100 and geopolitical uncertainty influencing global markets, the Federal Reserve’s battle against inflation appears far from finished.
For investors, the message from financial markets is becoming increasingly clear: the possibility of higher interest rates is once again a central risk — and the next few inflation reports could determine just how much further the Federal Reserve is willing to go.