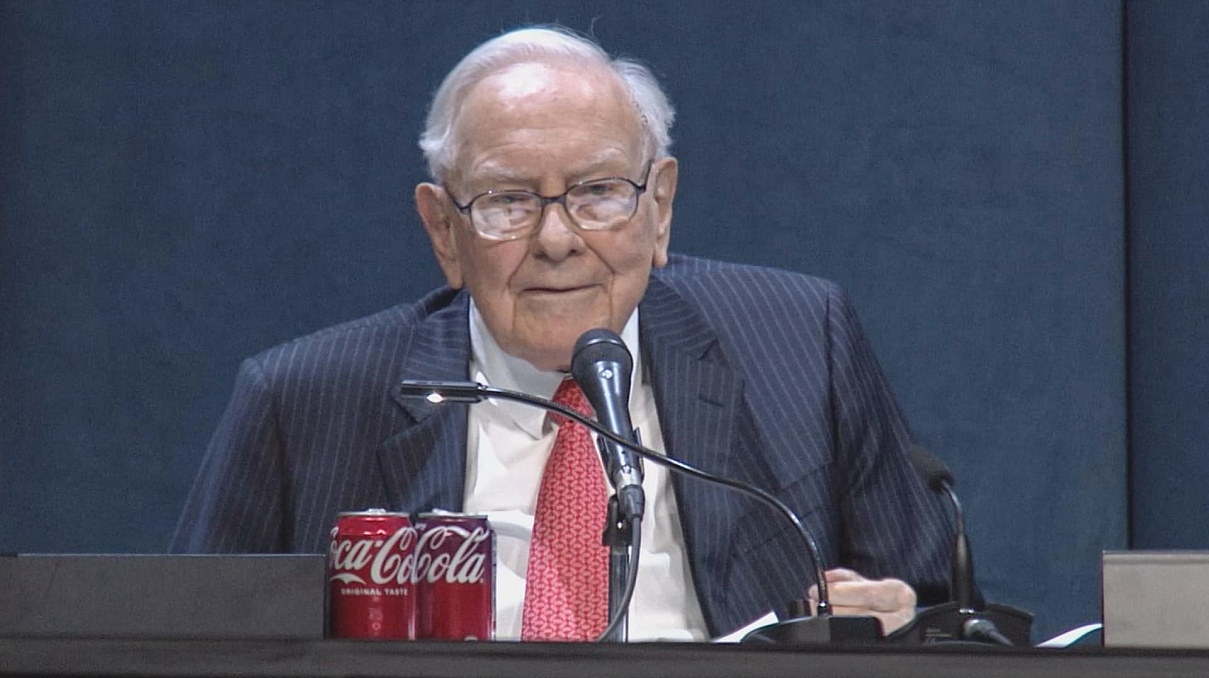
One of Warren Buffett’s most criticized acquisitions may be turning into one of Berkshire Hathaway’s most valuable industrial investments.
Precision Castparts, the aerospace and industrial components manufacturer Berkshire acquired for $37.2 billion in 2016, is attracting renewed attention after a major transaction involving one of its competitors suggested that the company could potentially command a valuation approaching $100 billion.
The development represents a remarkable reversal for an acquisition that once forced Berkshire to record an approximately $11 billion write-down.
Buffett openly acknowledged that Berkshire had paid too much for Precision Castparts after the Covid pandemic devastated commercial aviation and sharply reduced demand throughout the aerospace supply chain.
Six years after that write-down, however, conditions have changed dramatically.
Commercial aerospace demand has recovered, critical engine components are in tight supply, and another unexpected source of demand is emerging from the artificial intelligence infrastructure boom.
Natural gas turbines used to generate electricity for data centers require some of the same highly specialized metal components that Precision Castparts has spent decades manufacturing.
A major acquisition announced this week by GE Aerospace has now provided investors with a new benchmark for determining what businesses such as Precision Castparts could be worth.
Berkshire Paid $37.2 Billion for Precision Castparts
Berkshire Hathaway completed its acquisition of Precision Castparts in 2016 for approximately $37.2 billion.
The transaction was enormous even by Berkshire’s standards.
Precision Castparts specializes in highly engineered metal components used in demanding industrial applications.
Its products include critical parts used inside aircraft engines and industrial gas turbines.
These are not ordinary manufactured components.
Engine parts can operate under extreme temperatures, pressure and mechanical stress.
Producing them requires specialized materials, advanced manufacturing processes and strict quality standards.
Those characteristics create barriers to entry.
Aircraft manufacturers and engine companies cannot easily replace suppliers of mission-critical components without extensive testing and qualification.
That industrial position was one of the characteristics that originally attracted Buffett.
Buffett Later Admitted Berkshire Paid Too Much
The acquisition did not initially develop as Buffett expected.
The Covid pandemic brought global air travel to a historic collapse.
Airlines grounded aircraft.
Manufacturers reduced production.
Demand for new commercial planes and related components fell sharply.
Precision Castparts was directly exposed to that downturn.
Berkshire ultimately recorded an approximately $11 billion write-down related to the acquisition.
Buffett did not attempt to hide the mistake.
He acknowledged that Precision Castparts remained a strong company and a leader in complex metal manufacturing, but admitted that he had been too optimistic about its future earnings.
In other words, Buffett’s mistake was not necessarily buying a poor business.
It was paying a price that assumed more profit than the company was ultimately able to generate under the conditions that followed.
The distinction is important in investing.
A great company can still become a bad investment if purchased at an excessively high valuation.
Aerospace Demand Has Recovered
The environment surrounding Precision Castparts today looks considerably different.
Commercial aviation has recovered from the pandemic shock.
Aircraft manufacturers and engine producers are working through substantial demand while supply chains remain constrained.
Many aerospace components require long manufacturing lead times and specialized production capacity.
Increasing output is not as simple as adding another generic manufacturing line.
Suppliers need equipment, skilled workers, specialized materials and customer qualification.
This can create bottlenecks when demand accelerates rapidly.
Precision Castparts’ ability to manufacture difficult, high-value components therefore becomes more valuable when supply is tight.
Turbine Blades Are Critical Components
Among the products associated with Precision Castparts are turbine components used in aircraft engines and industrial gas turbines.
Turbine blades operate in exceptionally difficult environments.
They must withstand extreme heat while rotating at high speeds and maintaining structural integrity.
Failure is not acceptable.
That requires sophisticated engineering and manufacturing capabilities.
Companies capable of reliably producing these components at scale occupy strategically important positions within the aerospace supply chain.
As aircraft production increases, demand for engine components rises with it.
But aerospace is no longer the only market attracting attention.
The expansion of artificial intelligence is creating another potential source of demand.
AI Data Centers Are Creating Demand for Gas Turbines
The artificial intelligence boom is often associated with semiconductors, cloud computing and software.
Increasingly, however, investors are recognizing that AI is also an energy infrastructure story.
Training and operating advanced AI models requires enormous computing capacity.
That computing capacity is concentrated in data centers consuming large quantities of electricity.
As technology companies expand their AI infrastructure, securing sufficient power has become one of the industry’s biggest challenges.
Natural gas turbines are one option for generating reliable electricity.
Those turbines require advanced metal components capable of operating under extreme conditions — precisely the type of products manufactured by companies such as Precision Castparts.
This creates an unusual connection between a traditional industrial manufacturer and one of the fastest-growing technology trends in the world.
GE Aerospace Deal Provides a New Valuation Benchmark
Investor interest in Precision Castparts increased after GE Aerospace announced an agreement to acquire Consolidated Precision Products.
CPP is an important competitor in the precision aerospace components market.
GE Aerospace agreed to pay approximately $11.75 billion for the company.
The valuation attracted attention because the transaction was reportedly priced at approximately 26 times projected 2027 earnings before interest, taxes, depreciation and amortization, or EBITDA.
A 26-times forward EBITDA multiple is a substantial valuation for an industrial business.
The price suggests that strategic buyers are willing to pay significant premiums for scarce aerospace manufacturing capabilities.
That has obvious implications for Precision Castparts.
Could Precision Castparts Be Worth $100 Billion?
Applying a similar valuation multiple to Precision Castparts has produced estimates suggesting Berkshire’s subsidiary could theoretically be worth around $100 billion.
That figure should be treated carefully.
Berkshire has not announced that Precision Castparts is worth $100 billion.
The company is not publicly traded independently, meaning there is no market price continuously establishing its valuation.
The estimate is instead an extrapolation based on the multiple GE Aerospace agreed to pay for Consolidated Precision Products.
Different companies can deserve different valuation multiples depending on growth, margins, customer relationships, business mix, capital requirements and other factors.
Still, the comparison is significant.
Recent estimates had placed Precision Castparts’ value closer to approximately $60 billion to $75 billion.
A potential valuation approaching $100 billion would make the subsidiary considerably more valuable than Berkshire’s original $37.2 billion purchase price.
The Write-Down Did Not Mean the Business Was Permanently Impaired
The situation also demonstrates an important accounting concept.
When Berkshire recorded the $11 billion write-down, it acknowledged that the accounting value associated with the acquisition was too high relative to expected future economics at the time.
That did not mean Precision Castparts could never recover.
Economic conditions change.
Demand changes.
Industry capacity changes.
Competitive positions can become more valuable.
A business that appears significantly impaired during a historic collapse in commercial aviation can look very different years later when aerospace supply chains are tight and industrial turbine demand is increasing.
The write-down reflected Berkshire’s assessment during a particular period.
It did not place a permanent ceiling on the company’s future value.
Precision Castparts May Be One of Berkshire’s Most Valuable Businesses
If higher estimates prove reasonable, Precision Castparts could rank among Berkshire Hathaway’s most valuable operating subsidiaries.
Berkshire owns a diverse collection of businesses spanning insurance, railroads, energy, manufacturing, retail and services.
Unlike Berkshire’s publicly traded investments, many of these subsidiaries do not have visible market valuations.
Investors therefore need to estimate what individual businesses might be worth.
That process can become particularly important when comparable companies are acquired.
A large transaction involving a close competitor provides a real-world valuation benchmark.
The GE Aerospace deal has done exactly that for the precision-components industry.
Berkshire Shares Have Shown Relative Strength
Berkshire Hathaway shares gained nearly 0.9% this week, according to the information provided, even as the broader market declined.
The move represents modest relative strength.
However, Berkshire’s Class B shares remain more than 10% behind the S&P 500 on a year-to-date basis.
Precision Castparts alone is unlikely to determine Berkshire’s share price.
The conglomerate is too large and diversified for a single subsidiary to completely drive valuation.
But if investors conclude that one of Berkshire’s major industrial businesses is worth tens of billions more than previously assumed, it can affect assessments of the conglomerate’s overall intrinsic value.
Limited Disclosure Makes Valuation More Difficult
One reason Precision Castparts’ potential value has received relatively limited attention is Berkshire’s unusual approach to investor relations.
The company does not operate like many large public corporations.
CEO Greg Abel, following the culture established under Buffett, does not regularly participate in the traditional cycle of analyst calls and investor events used by many corporate executives.
Berkshire also contains numerous operating businesses inside a single enormous organization.
That can make it difficult for investors to assign precise values to individual subsidiaries.
Some market observers believe the limited communication can reduce visibility into businesses such as Precision Castparts.
A standalone publicly traded aerospace supplier might receive extensive analyst coverage.
Inside Berkshire, the same business can attract much less attention.
Buffett’s Investment Philosophy Has Always Accepted Mistakes
The Precision Castparts story also provides an example of an important feature of Buffett’s investment career.
Even highly successful investors make major mistakes.
Buffett has repeatedly acknowledged errors rather than presenting every Berkshire investment as a success.
The original purchase price for Precision Castparts became one of those mistakes in his own assessment.
But overpaying does not necessarily mean an investment can never become valuable.
If a high-quality business continues operating for decades and its competitive advantages remain intact, earnings can eventually grow into a previously excessive purchase price.
Whether Precision Castparts ultimately proves to be an exceptional Berkshire investment will depend on its future cash generation, not simply a theoretical valuation based on a competitor’s acquisition.
Still, the current industry environment looks considerably more favorable than it did when Berkshire recorded the write-down.
A Separate Political Controversy Involved Buffett’s Image
Buffett also appeared in an unrelated political controversy in Nebraska’s 2nd Congressional District.
Republican candidate Brinker Harding used an image of Buffett in a campaign advertisement without permission.
Susie Buffett requested that the advertisement be removed, saying its use of her father’s image created the impression that Buffett had endorsed the candidate when no such endorsement had been given.
Harding’s campaign responded by accelerating the introduction of a new advertisement that did not include Buffett’s image.
The episode illustrates the unusual public significance of Buffett’s reputation.
Although best known as an investor and Berkshire Hathaway’s longtime leader, his image can carry political and economic symbolism far beyond the investment industry.
September 11 Also Shaped Buffett’s Thinking About Risk
Buffett’s reflections on risk extend beyond individual acquisitions.
He has previously discussed how the September 11, 2001 attacks affected Berkshire’s insurance operations.
The attacks demonstrated that terrorism risk needed to be incorporated more explicitly into insurance underwriting.
For Berkshire, which operates major insurance and reinsurance businesses, rare catastrophic events can create enormous financial consequences.
The lesson aligns with a broader principle visible throughout Buffett’s career: risks that appear unlikely cannot automatically be treated as impossible.
That philosophy has influenced how Berkshire thinks about insurance exposure, financial strength and the amount of capital it maintains.
Precision Castparts Shows How Investment Narratives Can Change
Few Berkshire acquisitions demonstrate the changing nature of investment narratives as clearly as Precision Castparts.
Berkshire paid $37.2 billion for the company in 2016.
Years later, Buffett admitted that the purchase price had been too high, and Berkshire recorded an approximately $11 billion write-down as the pandemic devastated aerospace demand.
At that moment, Precision Castparts looked like one of Buffett’s most expensive mistakes.
Today, the picture is different.
Commercial aerospace demand has recovered.
Supply chains for highly specialized engine components remain tight.
AI data centers are creating additional demand for power infrastructure, including natural gas turbines that use advanced components similar to those manufactured by Precision Castparts.
Then came GE Aerospace’s $11.75 billion agreement to acquire Consolidated Precision Products at roughly 26 times projected 2027 EBITDA.
Using that transaction as a benchmark suggests Precision Castparts could potentially command a valuation around $100 billion, although that remains an estimate rather than an official Berkshire valuation.
If the estimate is even approximately correct, an acquisition once associated with an $11 billion write-down could now represent one of the most valuable industrial assets inside Berkshire Hathaway.
For investors, the larger lesson is not that Buffett’s original purchase price has suddenly been proven correct.
It is that the value of a high-quality industrial business can change dramatically as supply, demand and technology reshape its markets.
Precision Castparts survived one of the worst aerospace downturns in history.
Now it finds itself positioned at the intersection of two powerful trends: the recovery and expansion of global aviation and the enormous energy requirements created by artificial intelligence.
A decade after Berkshire’s $37.2 billion acquisition, that combination is giving investors a reason to look again at a deal that once appeared to be one of Warren Buffett’s clearest mistakes.