Japan’s foreign exchange reserves suffered their largest monthly decline on record in August, falling by approximately $80 billion as authorities continued an aggressive campaign to support the yen while rising global bond yields reduced the value of securities held in the country’s reserve portfolio.
Foreign reserves declined 6.18% to $1.207 trillion in August from $1.287 trillion in July, according to Japan’s finance ministry.
The decline marked the fourth consecutive month of falling reserves and the fastest monthly contraction since comparable records began in 2000.
The extraordinary move reflects two major forces affecting Japan’s reserve position: direct intervention in foreign exchange markets and valuation changes in government bonds as global yields climbed.
Japan has spent unprecedented amounts attempting to stabilize its currency in 2026. Finance ministry data show approximately 27.1 trillion yen has been deployed in foreign exchange interventions so far this year, already surpassing the previous full-year record of 20.4 trillion yen established in 2003.
Despite the dramatic decline in reserves, market analysts have emphasized that the move primarily reflects deliberate policy actions and market valuation changes rather than evidence of immediate financial distress.
Japan’s Reserves Fall to $1.207 Trillion
Japan entered August with approximately $1.287 trillion in foreign reserves.
By the end of the month, that figure had fallen to $1.207 trillion.
An $80 billion monthly decline is significant even for a country with one of the world’s largest reserve portfolios.
Foreign exchange reserves provide governments and central authorities with financial resources that can be used for several purposes, including currency-market intervention.
Reserve portfolios can contain foreign government bonds, deposits and other highly liquid assets denominated in currencies such as the U.S. dollar.
For Japan, those reserves provide the financial firepower required when authorities decide that movements in the yen have become excessive or disorderly.
That mechanism has become particularly important in 2026.
Why Currency Intervention Reduces Foreign Reserves
The mechanics behind Japan’s intervention are relatively straightforward.
When authorities want to strengthen the yen against the dollar, they can sell dollar-denominated assets or dollars held in reserves and use the proceeds to purchase yen in the foreign exchange market.
That increases demand for the Japanese currency while increasing the supply of dollars.
If the intervention is sufficiently large, it can push the yen higher.
But there is a cost.
Every time Japan sells part of its foreign currency holdings to buy yen, its reserve position can decline.
This helps explain why the unprecedented intervention activity recorded this year has coincided with falling reserves.
An unnamed finance ministry official cited in the original reporting linked the August decline partly to the government’s foreign exchange operations.
Japan Has Already Broken Its Intervention Record
The scale of Japan’s 2026 currency intervention has been extraordinary.
According to finance ministry figures, authorities have spent approximately 27.1 trillion yen supporting the currency so far this year.
That has already surpassed the previous annual intervention record of 20.4 trillion yen established in 2003.
The interventions have also occurred in several major waves.
Approximately 11.73 trillion yen was deployed during April and May.
An even larger operation followed at the end of July, when authorities spent approximately 15.4 trillion yen.
Together, these interventions demonstrate how seriously policymakers have viewed the yen’s decline.
Currency intervention is generally not the first tool authorities want to use repeatedly.
Markets are enormous, and private trading volumes can overwhelm government intervention if investors believe the underlying economic forces pushing a currency lower remain unchanged.
For that reason, interventions can sometimes be most effective when they alter market psychology or are supported by broader changes in monetary and economic conditions.
Yen Reached a 40-Year Low in July
The pressure on Japanese policymakers became particularly intense during July.
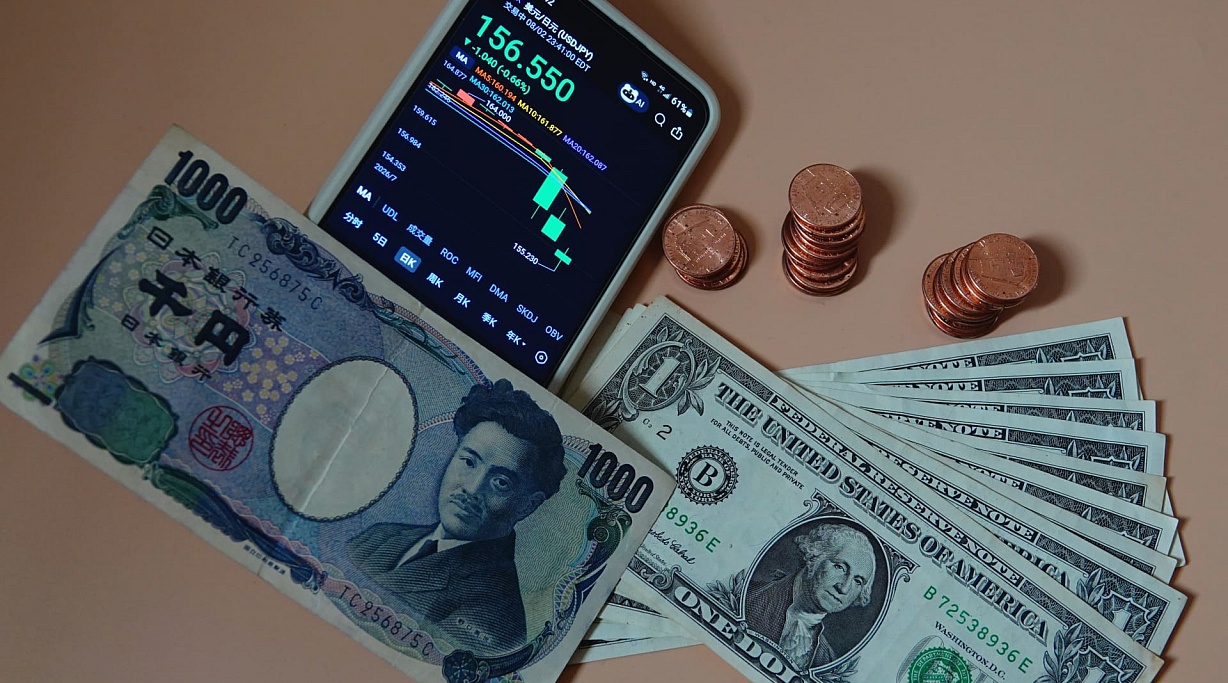
The yen weakened to 163.98 against the U.S. dollar on July 23, its lowest level in approximately 40 years.
A weaker currency can produce both benefits and costs for Japan.
Export-oriented companies can benefit because revenue earned overseas becomes more valuable when converted back into yen.
Japanese products can also become more competitively priced in foreign markets.
But a sharply weaker yen makes imports more expensive.
That is particularly important for a country that imports significant quantities of energy, raw materials and other goods.
Higher import costs can increase inflation and pressure household purchasing power.
When currency depreciation happens too rapidly, policymakers can become concerned not only about the exchange rate itself but also about market stability and its broader economic consequences.
Intervention Has Helped the Yen Recover
Since reaching its July low, the yen has strengthened.
By early September, it was trading around 155.98 per dollar, compared with 163.98 on July 23.
That represents a meaningful recovery.
However, attributing the entire move to government intervention would oversimplify the situation.
Currency markets respond to numerous factors simultaneously.
Interest-rate expectations, inflation, economic growth, central bank policy, geopolitical developments and investor positioning can all influence exchange rates.
Japan’s intervention can affect short-term supply and demand for the yen, but longer-term currency trends are generally shaped by broader economic forces.
The question for policymakers is whether intervention can provide enough stability while those underlying conditions evolve.
U.S. Joined Japan in Coordinated Intervention
One of the most significant developments occurred at the end of July, when Japan and the United States reportedly conducted coordinated action to support the yen.
The operation marked the first joint intervention in support of the Japanese currency since 1998.
According to the information provided, the United States assisted by selling euros as part of the effort to reinforce the yen.
Coordinated intervention can carry greater psychological weight than action taken by one country alone.
Currency traders may interpret cooperation between major governments as a stronger signal that policymakers are uncomfortable with current exchange-rate movements.
The effectiveness of intervention, however, still depends on market conditions.
Even large government transactions operate within a global foreign exchange market where enormous amounts of currency change hands every day.
Rising Bond Yields Also Reduced Reserve Values
Currency intervention was not the only factor behind the August decline in Japanese reserves.
Higher global bond yields also affected the value of securities held in the reserve portfolio.
Government bonds generally have an inverse relationship between prices and yields.
When yields rise, the market value of existing bonds typically falls.
This happens because newly issued bonds offering higher yields become more attractive than older securities paying lower rates.
To compensate, the market price of the older bonds declines.
Japan holds substantial foreign assets as part of its reserves.
If the market value of those securities falls because global yields rise, the reported value of the reserve portfolio can decline even without Japan selling every affected asset.
This distinction is important when interpreting the headline $80 billion drop.
Part of the decline represents assets being used for intervention, while another part may reflect changes in market valuation.
Global Bond Markets Have Been Under Pressure
The reserve decline occurred during a period of significant movement across international bond markets.
Yields in Germany, the United Kingdom and the United States climbed to multiyear highs, influencing fixed-income markets globally.
Rising U.S. Treasury yields are particularly important because Treasury securities play a central role in global financial markets and foreign reserve portfolios.
When Treasury yields rise substantially, bond prices fall.
That can affect the reported dollar value of reserve assets held by foreign governments.
The movement also matters for exchange rates.
Higher U.S. yields can make dollar-denominated assets more attractive to international investors.
If investors can earn higher returns from U.S. securities, demand for dollars may increase.
That can create additional pressure on currencies such as the yen.
Japan therefore faces a complicated relationship between global bond yields and currency policy.
Interest-Rate Differences Matter for the Yen
One of the most important long-term drivers of exchange rates is the difference in interest rates between countries.
Investors often compare the potential return available from holding assets denominated in different currencies.
When U.S. interest rates are significantly higher than Japanese rates, dollar-denominated investments can appear more attractive.
Investors may borrow or sell lower-yielding currencies and allocate capital toward higher-yielding assets.
These capital flows can put downward pressure on the lower-yielding currency.
Government intervention can temporarily push against those forces.
But if interest-rate differences remain large, authorities may need substantial resources to counter the market.
This is why foreign exchange intervention cannot be evaluated independently from monetary policy.
Analysts Say the Reserve Drop Does Not Signal a Financial Crisis
An $80 billion decline in reserves naturally attracts attention.
However, analysts have cautioned against interpreting the number as evidence that Japan is experiencing a financial crisis.
Masahiko Loo, senior fixed income strategist at State Street Investment Management, said the decline primarily reflects Japan’s recent dollar-selling and yen-buying interventions.
In other words, reserves are declining partly because the government is deliberately using them.
That is fundamentally different from a country losing reserves because investors are rapidly withdrawing capital and authorities are struggling to meet external obligations.
Japan still held approximately $1.207 trillion in reserves after the August decline.
The country therefore retains a very large financial buffer.
The more important question is how long authorities are willing to continue using those reserves if the yen comes under renewed pressure.
Intervention Cannot Replace Economic Fundamentals
Large reserves give Japan substantial capacity to intervene, but intervention has limitations.
Governments can influence currency markets, particularly over shorter periods.
Sustaining a long-term exchange-rate trend is more difficult when underlying economic conditions point in the opposite direction.
If investors continue to expect significantly higher returns in U.S. assets than in Japanese assets, demand for dollars may remain strong.
Likewise, changes in inflation, economic growth or central bank policy can alter the attractiveness of the yen.
For intervention to produce lasting results, market fundamentals eventually need to become more supportive.
This does not make intervention ineffective.
It can slow disorderly moves, discourage speculative positioning and signal that policymakers are prepared to act.
But it is one tool within a much larger economic framework.
Japan Still Has Considerable Financial Firepower
Despite the record monthly decline, Japan’s reserve position remains substantial.
At $1.207 trillion, the country still possesses significant foreign assets that can potentially be deployed if authorities determine that additional intervention is necessary.
However, policymakers cannot treat reserves as unlimited.
Repeated interventions at the scale seen in 2026 would continue reducing the reserve pool.
Authorities therefore need to consider both the immediate benefits of supporting the currency and the longer-term cost of continuously selling foreign assets.
Market participants are likely to watch future finance ministry data closely for evidence of additional intervention.
Sudden movements in the yen could also raise speculation that authorities have returned to the market.
What Investors Should Watch Next
Several factors will determine whether Japan needs to continue its aggressive currency strategy.
The first is the yen itself.
If the currency remains relatively stable or strengthens further, the need for large-scale intervention may decline.
A renewed move toward previous lows could increase pressure on policymakers to act again.
Global bond yields will also matter.
If U.S. and European yields continue climbing, the valuation of Japan’s foreign bond holdings could remain under pressure.
Interest-rate expectations are equally important.
Changes in monetary policy expectations in Japan and the United States can alter the yield differential between the two countries and therefore influence demand for the yen.
Finally, investors will watch for additional signs of international coordination.
The joint intervention with the United States demonstrated that Japan is not necessarily acting alone when currency movements become sufficiently concerning.
Japan Faces a Difficult Currency Balancing Act
The record $80 billion decline in Japan’s foreign reserves illustrates the extraordinary scale of the country’s battle against yen weakness.
Reserves fell 6.18% in August, from $1.287 trillion to $1.207 trillion, marking the fourth consecutive monthly decline and the sharpest contraction since records began in 2000.
Japan has already spent approximately 27.1 trillion yen on foreign exchange intervention in 2026, surpassing the previous annual record of 20.4 trillion yen set in 2003.
Those interventions have coincided with a recovery in the yen from its 40-year low of 163.98 per dollar on July 23 to around 155.98 in early September.
At the same time, rising global bond yields have reduced the market value of securities held within Japan’s reserves, adding another source of pressure to the headline reserve figure.
For investors, the key distinction is that the decline primarily reflects deliberate policy actions and valuation effects rather than clear evidence of financial distress.
Japan still holds more than $1.2 trillion in reserves.
But the events of 2026 demonstrate that even one of the world’s largest reserve holders faces difficult choices when global interest rates, bond markets and currency movements move sharply against it.
The next phase will depend on whether the yen can maintain its recovery without another massive intervention — or whether Japan will once again need to deploy its considerable financial resources to defend the currency.